Latest posts
-
The 50/30/20 Rule, Explained Simply
The 50/30/20 Rule Explained: Does It Still Work in 2026? The 50/30/20 rule takes something that feels complicated — managing every dollar of your paycheck — and reduces it to three numbers you can remember without ever opening a spreadsheet. Split your after-tax income into 50% for needs, 30% for wants, and 20% for savings…
-
Talking to Your Partner About Money Without It Turning Into a Fight
Talking to your partner about money without it turning into a fight usually comes down to one realization most couples never quite land on: the argument was never really about the number on the receipt. It’s about safety, trust, and old wounds neither person signed up to bring into the relationship, but both did anyway.…
-
Tax Refund vs Tax Bill: What Your W-4 Is Really Telling You
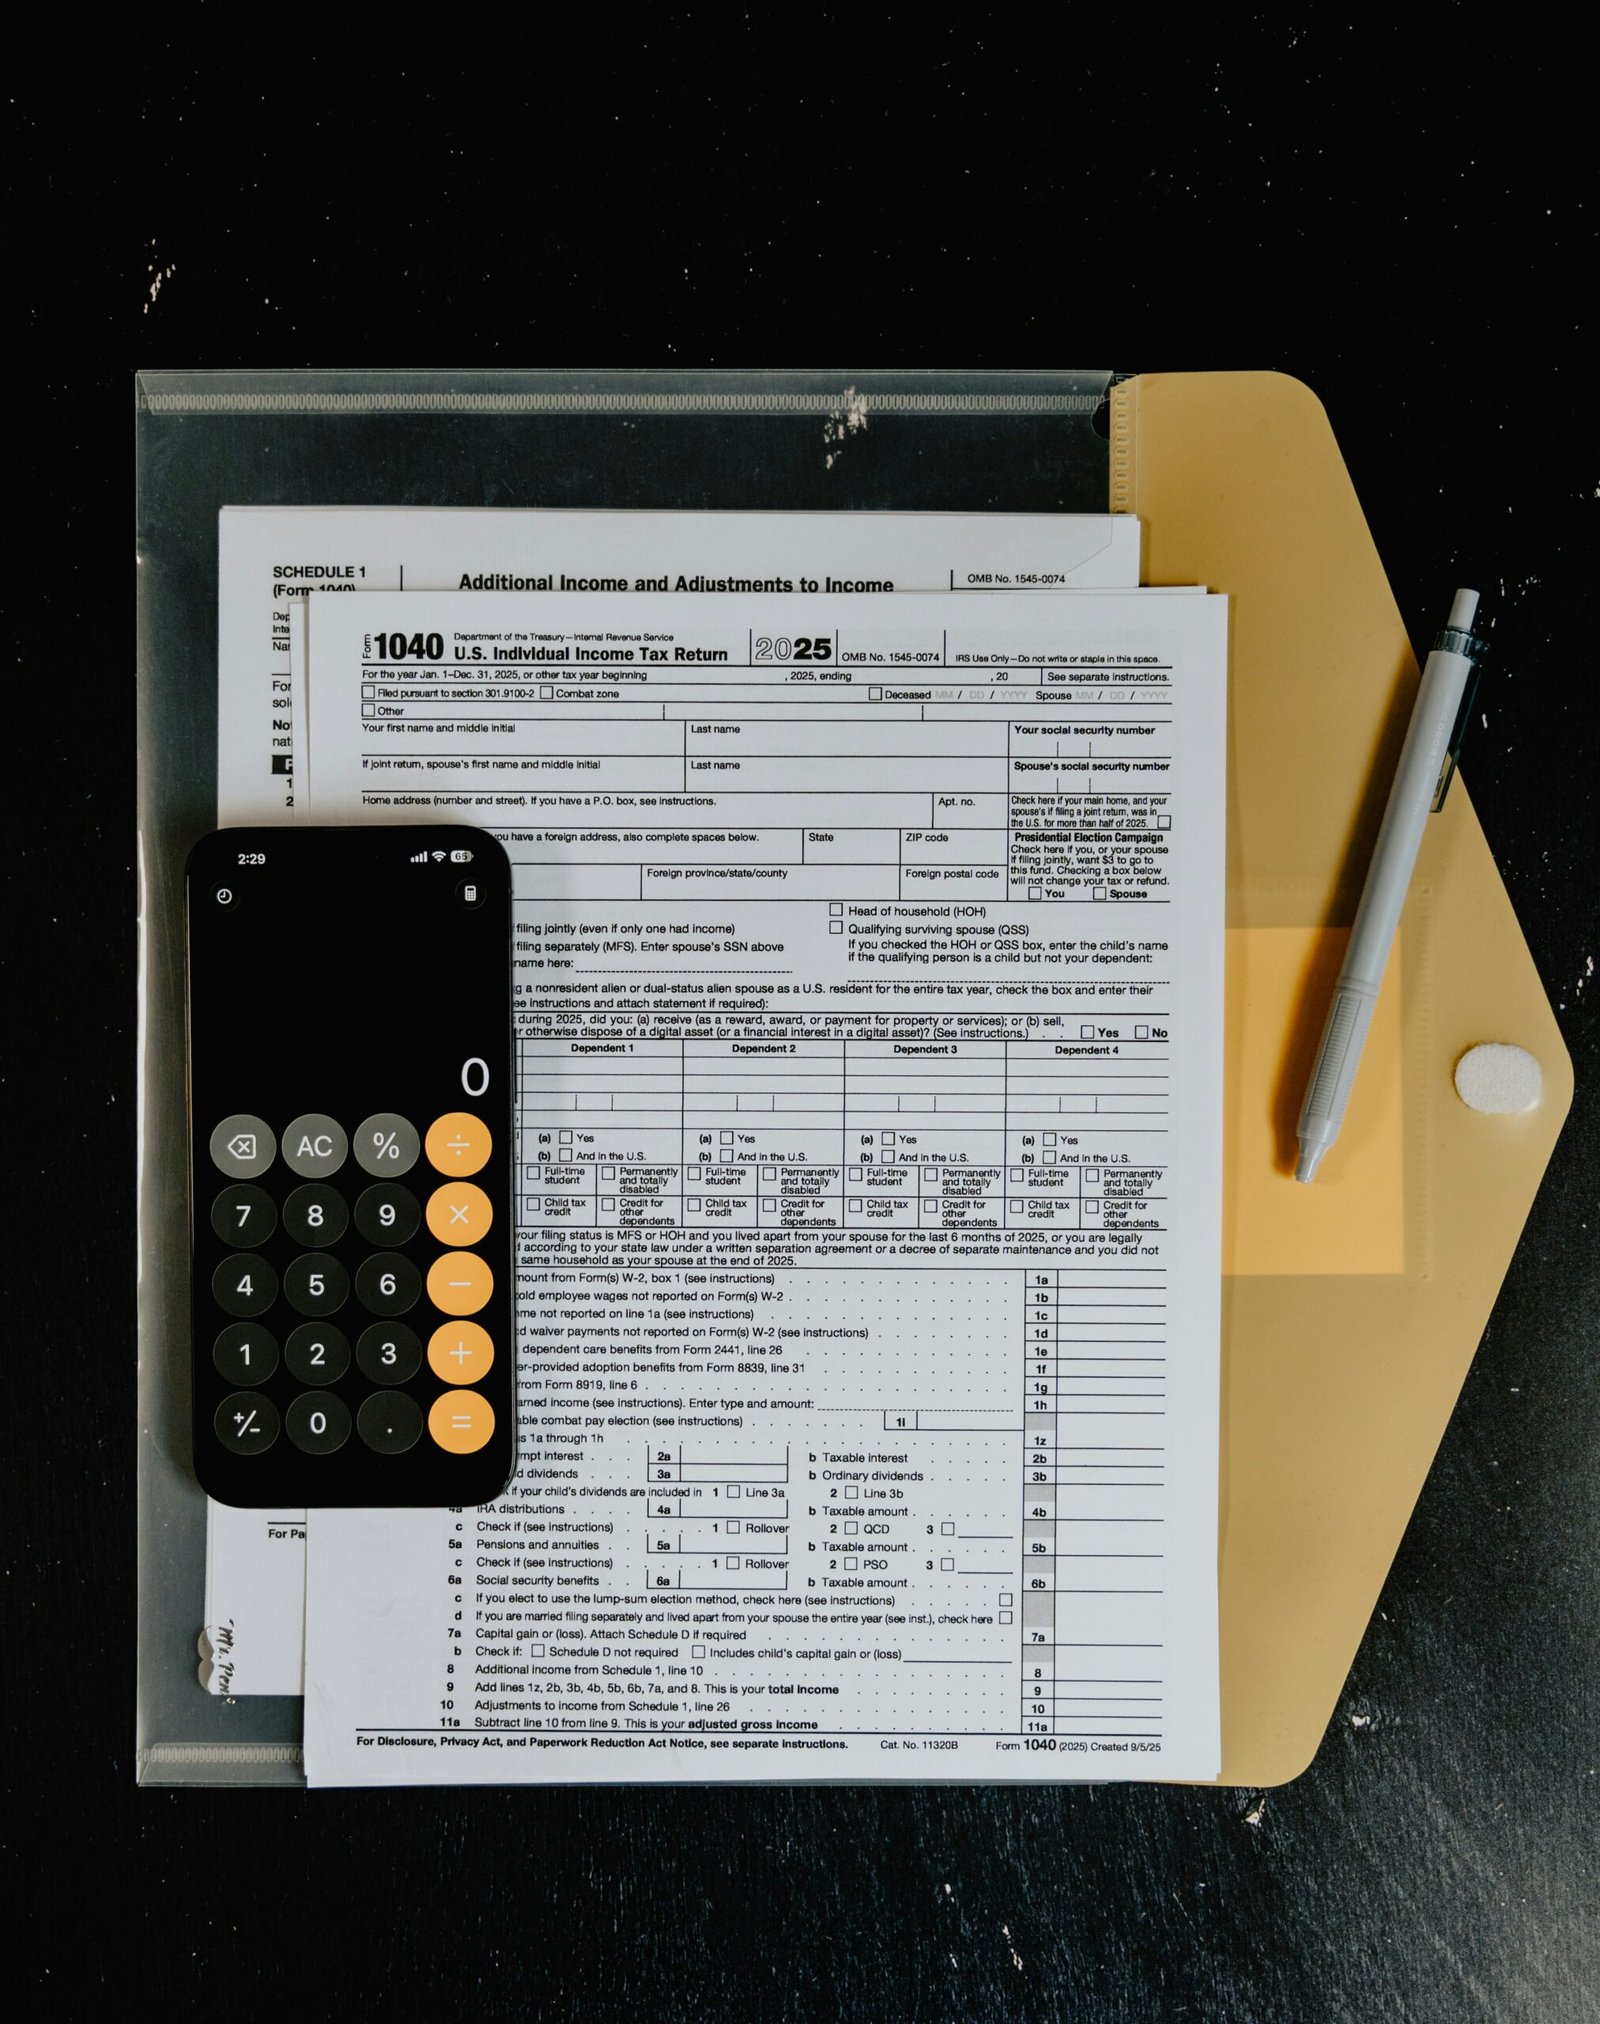
Your W4 Form 2026 is the quiet reason two coworkers can file their taxes in the same week and walk away with completely different results. One gets a $4,200 refund and books a vacation with it. The other opens a letter that says he owes $1,900 (money he doesn’t currently have sitting around). Neither one…
-
Sinking Funds: Saving for Irregular Expenses Without Going Into Debt
Saving for irregular expenses without going into debt starts with naming the actual problem correctly. The car needing new brakes, the holidays showing up every December, the annual insurance premium renewing — none of these are surprises. You knew they were coming. They just never had a line item in the monthly budget, which is…
-
Index Funds Explained for People Who Hate Investing Jargon
Index funds explained without the jargon comes down to one plain-English sentence: it’s a way to buy a tiny slice of hundreds or thousands of companies at once, with one purchase, instead of trying to guess which single company will do well. Everything else — expense ratios, passive management, dollar-cost averaging — is just detail…
-
Your Utility Bill Doesn’t Have to Be This High
Your utility bill doesn’t have to be this high, and the reason it feels impossible to lower usually comes down to one blind spot: most people only ever attack half the problem. A $220 bill doesn’t tell you whether the real issue is how much energy you’re using, what rate you’re paying per kilowatt-hour, or…
-
How to Negotiate a Lower Interest Rate on Debt & Credit: The Best Guide for 2026
How to negotiate a lower interest rate on debt and credit starts with a number worth knowing before you ever pick up the phone: the average credit card interest rate sat at 21.52% as of February 2026, according to the Federal Reserve Bank of St. Louis. If your rate is anywhere near or above that,…
-
Saving for Retirement in Your 20s and 30s: The Best Tips for 2026
Saving for retirement in your 20s and 30s comes down to a math problem that favors you enormously right now, and gets meaningfully harder to win with every year you wait. A median worker under 35 currently has about $18,880 saved for retirement — nowhere close to the commonly cited target of having 1x your…
-
A Budget That Actually Works When Your Income Changes Month to Month
A budget that actually works when your income changes month to month has to break one rule that every traditional budgeting method assumes without saying it out loud: that you know how much money is coming in before the month starts. Freelancers, gig workers, and commission-based earners don’t get that luxury. One month lands $8,000.…
-
The Number That Quietly Controls Your Interest Rates
The number that quietly controls your interest rates isn’t your income, your job title, or how much you have in savings. It’s a three-digit figure between 300 and 850 that most people check once a year, if that — and it silently determines whether your next mortgage, car loan, or credit card costs you thousands…