Latest posts
-
Crypto Retirement Portfolio Allocation: A Risk-Based Framework
How much of a retirement portfolio should be crypto, if any? In my view, the useful question isn’t “crypto or no crypto.” It’s how big the slice should be and when to start shrinking it. Below is a framework I built around risk tolerance and timeline, with the arithmetic shown. The percentages are my illustrations,…
-
Your Savings Goal Tracker Breaks If You’re Saving in Crypto
Tracking a savings goal in crypto takes a different approach than tracking one in a savings account, because the balance moves with the market and not only with what you put in. This article builds a simple goal system first, then shows the one change that crypto requires. The system is my own suggestion; the…
-
Subtracting Crypto From Your Life Insurance Coverage Calculation
Term life insurance is often assumed to cost more than it does. This post walks through a simple way to size coverage, including how to treat crypto you count as savings. The title is about subtracting crypto from the calculation, and the encouraging point is that you control that choice: you can decide how much…
-
Lifestyle Inflation: Commit Your Raise in Advance and Save More
Lifestyle inflation means spending rises as income rises. This post leans on sources I can cite: a recent survey of higher earners, a long-studied way to commit raises to saving, and the arithmetic of what a raise can do. The good news is that the second item is a solution with published results. Lifestyle inflation:…
-
Can You Trust AI Budget Categories? A 10-Minute Weekly Check That Keeps Them Accurate
Categorization is the focus of this guide. AI budgeting apps sort your transactions into categories automatically, and most of the time that saves real effort. The useful question is not whether to trust them completely. It is how to set up a quick review habit so the occasional wrong label never distorts your budget. What…
-
Super Catch-Up Roth Mandate — What Changed for High Earners

Two retirement rules meet for some workers in their early 60s: a higher “super catch-up” limit for ages 60 to 63, and a requirement that catch-up contributions from higher earners be made as Roth contributions. Both are specific and numerical, which makes them easy to plan around. This post lays out the 2026 limits, who…
-
The Conversation That Could Save You $1,000+ This Year — And Most Renters Never Have It
Learning how to negotiate rent comes down to one conversation, and a short, respectful script is enough to start. Everything below is my own approach and reasoning, not a promise of savings. Results depend on your landlord and your local market. Why a Landlord Might Say Yes In my view, the logic is simple: an…
-
What to Actually Say the Next Time Money Comes Up With Your Partner
Learning how to talk to your partner about money starts with an admission: if bringing it up makes your stomach drop, you can start small. Everything below is my own approach to what to say and when, not research findings, so use the parts that fit you. The One Shift That Changes Everything In my…
-
Qualified Overtime Premium Deduction — The Real Math
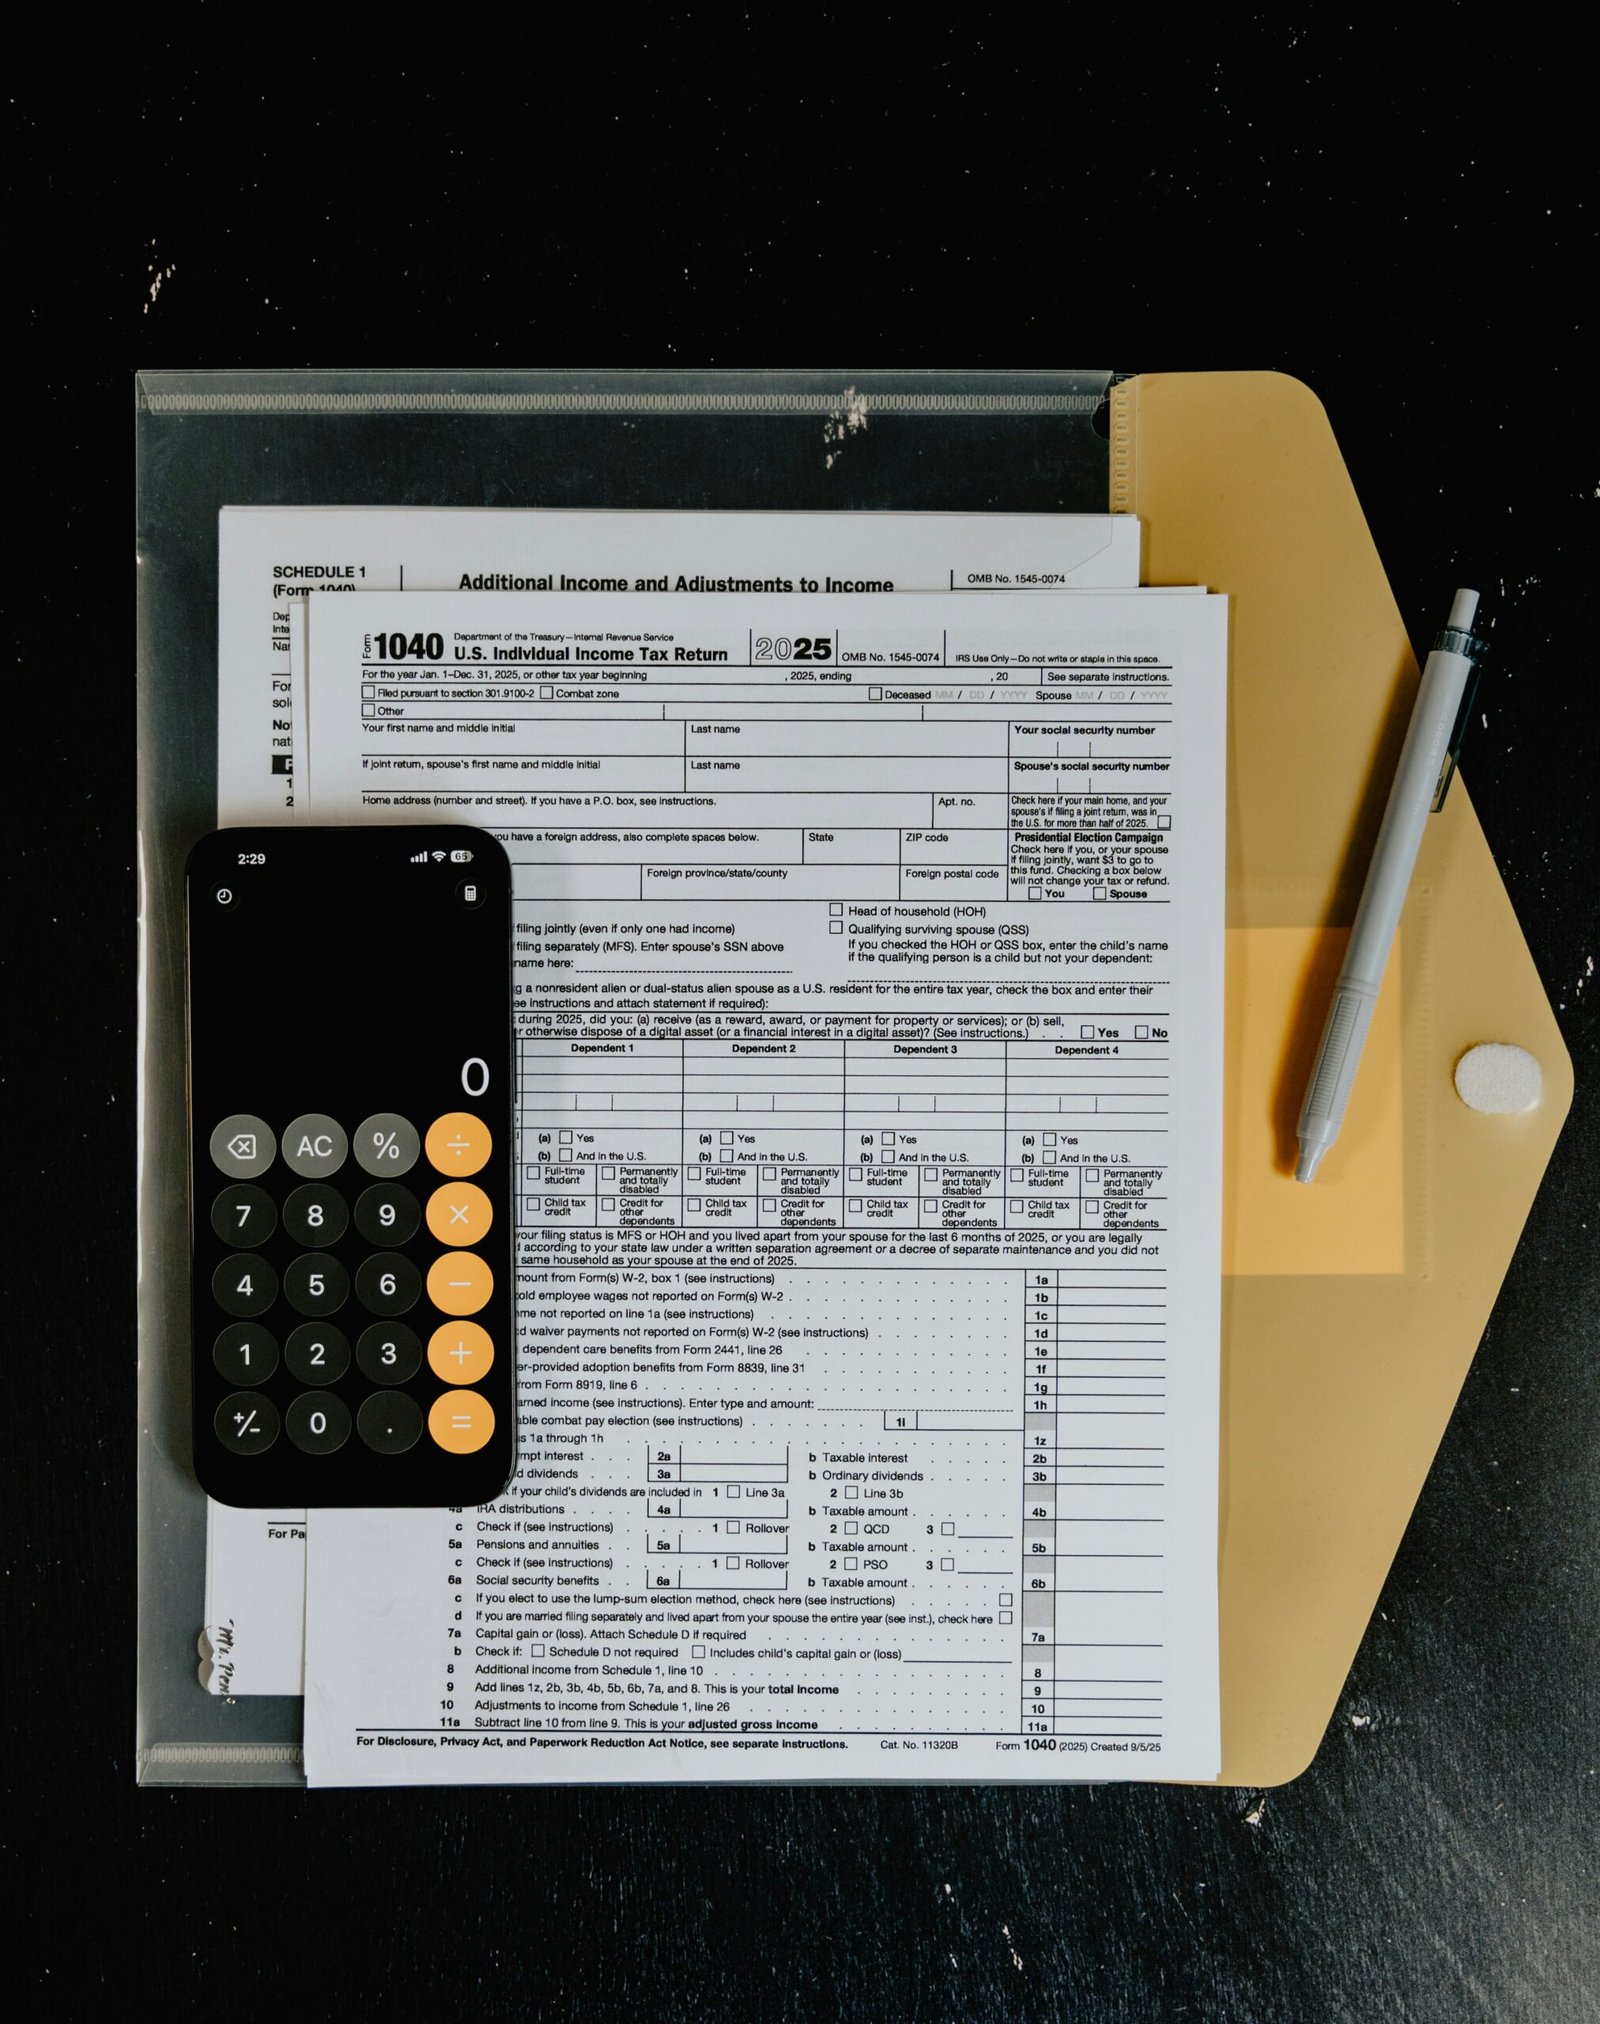
The qualified overtime deduction doesn’t make overtime pay tax-free. It’s a deduction for one specific slice of overtime pay, and the IRS’s August 2026 fact sheet spells out which slice. Here’s what it says, with my own comments labeled. The Actual Slice That Qualifies According to the IRS Fact Sheet FS-2026-13 (August 2026, which supersedes…
-
Sinking Fund Buckets: Split One Savings Account by Goal
A sinking fund is money set aside gradually for an expense you know is coming, such as a holiday, a car repair or an annual premium. Some banks let you split one savings account into named sub-balances, so each fund has its own line while the money stays in one place. The real point of…